Real estate is a risk mitigation tool. It provides inflation protection… What is nice about it is it’s a way to compound wealth over time.
– Chad Tredway, Head of Real Estate Americas, JP Morgan Asset Managment
By Realttorney®
Property ownership is a cornerstone of financial stability and wealth-building in the Philippines. However, the benefits of owning land can be maximized significantly when land titles are secured for these real properties.
Land titles are more than just pieces of paper. They are the linchpins of security, value, and opportunity in real estate ownership. The Supreme Court said that a certificate of title is merely an evidence of ownership or title over the particular property described therein.
This article delves into the reasons why landowners should prioritize obtaining land titles, highlighting the legal security, enhanced property value, and access to government programs and incentives that come with titled land instead of untitled ones.
The Legal Landscape of Land Titles in the Philippines. Before we delve into the benefits, it is crucial to understand the legal framework governing land titles in the Philippines. The Torrens system, adopted from the Massachusetts Land Registration Act of 1898, is the backbone of the country’s land registration system.
The Torrens system was adopted in this country because it was believed to be the most effective measure to guarantee the integrity of land titles and to protect their indefeasibility once the claim of ownership is established and recognized.
If this is so, what are the benefits for landowners if they apply for land titles over their lands?
Legal Security and Protection from Fraud. The Supreme Court said in Ebancuel vs. Ancierto, et al. (G.R. No. 214540, July 28, 2021) that “it is a fundamental principle in land registration that the certificate of title is evidence of an indefeasible and incontrovertible title over the property in favor of the person in whose name it is registered. The title serves as conclusive evidence of the ownership of the land described therein.”
The Torrens system ensures that land titles are conclusive against all claims except those noted in the certificate of title. By registering property under the Torrens system, landowners gain legal protection and recognition of their ownership against everyone else.
Hence, the person who has a Torrens title over the property is entitled to its possession. Likewise, the registered owner has the exclusive right to use, lease, or sell the land. Moreover, the landowner of a titled property has the right to the fruits of the land and to evict any illegal occupant on the said land.
In addition, the certificate of title becomes the best proof of ownership of a parcel of land. Having a Torrens title provides a stout defense against any fraudulent claims of ownership and possession. And, in the Philippines, there is no shortage of fraud committed against landowners.
Yet the Supreme Court has always ruled in favor of owners of registered lands with Torrens titles against usurpers and illegal occupants with unsubstantiated self-serving claims. However, at the same time, landowners must also know that the Torrens systemCANNOT be used for the perpetration of fraud against the real owner of the parcel of land.
It should be emphasized that the Torrens system merely confirms ownership but does not create it. What does this mean?
In a 1915 case, the Supreme Court held that “the registration under the Torrens system and the issuance of a certificate of title do not give the owner any better title than he had. He does not obtain title by virtue of the certificate.”
To be clear, the mere possession of a duly registered Torrens title does not automatically make the possessor a true owner of the parcel of land described therein. If a person acquires a certificate of title under the Torrens system which includes, by mistake or oversight, land that can no longer be registered under the system, he does not, by virtue of the certificate alone, become the owner of the land illegally included.
Furthermore, in various cases, the Supreme Court has always held that the Torrens systemCANNOT be used to protect a usurper from the true landowner, shield the commission of fraud, or enrich oneself at the expense of another.
Enhanced Property Value and Marketability. According to the Philippine Valuation Standard (PVS), which incorporates the International Valuation Standards (IVS), titled real properties are generally valued higher than untitled properties due to the legal security and protection they generally offer.
Why? Because potential buyers and investors have greater confidence in the legality and security of their investment in real properties with clear or “clean” certificates of title. Titled lands also provide clear ownership and protection against disputes and fraud.
Moreover, the process of verifying ownership and ensuring that there are no encumbrances is straightforward when a property is titled. This simplicity and transparency make titled properties more attractive to buyers, leading to quicker and more profitable sales.
The difference in value between titled and untitled parcels of land can vary significantly depending on location, market conditions, and other factors. However, according to experienced licensed real estate appraisers, it is common for titled properties to be valued 15-35% higher than untitled parcels of land.
This premium reflects the added security, marketability, and potential for financing that comes with having a certificate of title that is “clean”.
Access to Financing. Major financial institutions are more likely to approve loans or mortgages for titled land than untitled ones. Hence, securing a certificate of title opens up various opportunities for landowners to leverage their assets for financial gain and wealth-building.
For instance, a titled property can be used as collateral for a business loan, enabling the owner to invest in new ventures or improve existing ones. Or a titled agricultural land can serve as collateral to develop and make more productive a farm for the benefit of both the owner and the broader community.
Also, a titled residential land can be used to finance the building of a house or a renovation of an existing one. These cannot be done if the parcels of land are untitled. Hence, the benefits of having a titled parcel of land are irrefutable.
In conclusion, securing a certificate of title is a vital step for landowners in the Philippines. The benefits of legal security and protection, enhanced property value and marketability, and access to finance far outweigh the costs and effort involved in obtaining a land title.
As the Philippine real estate market continues to evolve, landowners who prioritize securing their Torrens certificates of titles will be in a better position to protect their investments, capitalize on market opportunities, and contribute to the nation’s development.
As a final note, always remember that a land title is not just a document. it is a key to security, prosperity, and peace of mind. Please don’t wait for disputes or missed opportunities to prompt you into action. Secure your land title today and reap the rewards of a well-protected and valuable property.
Transform your untitled land into an asset. Register now and equip yourself with the comprehensive knowledge to navigate the intricacies of land titling. Join us in this three-hour lecture that will walk you through the essentials of titling untitled lands in the Philippines.
The lecture is entitled, “Best Practices Guide to Titling Untitled Properties,” brought to you by the Center for Global Best Practices. For more information call Glaisie Falculan at (+63 949) 870-1832 or (+632) 8842-7148 or 59. Or kindly send her an email via glaisie.cgbp@yahoo.com.
Register now to begin 2025 with asset protection ideas.
——-
Atty. Jojo is a real estate attorney, an estate planning attorney, a licensed real estate broker, and a PRC-accredited Lecturer/ Speaker for Training Programs in Real Estate. He is a Chartered Trust and Estate Planning (CTEPTM) professional committed to educating Filipinos about the value and importance of incorporating real estate in their estate plan.
“In much of the rest of the world, rich people live in gated communities and drink bottled water… So that wealthy people in much of the world are insulated from the consequences of their actions.”
– Jared Diamond, Author and Pulitzer Prize Winner for “Guns, Germs and Steel”
By Realttorney®
Surely, not everyone is cut out to live in an exclusive or semi-exclusive subdivision that is governed by a Homeowners Association (HOA) with all its rules and regulations. There are pros and cons in living in a gated community – both, horizontal and vertical.
HOA-governed communities have mandatory dues and assessments which are oftentimes not commensurate to the level of service performed. Most of the time, the rules are too restrictive which create more hassle on the part of the member-homeowner.
On the other hand, HOA-governed communities are more secure, have generally better living environment and quality of life due to various amenities and recreational facilities. In addition, property values are maintained if not increase due to proper maintenance and enforcement of the rules.
Living in a gated community does not suit all types of personality. But, if you are convinced that living in a HOA-governed community is best suited for you, here are 5 steps to take to determine what community is best for you and your family.
First, when viewing a property to purchase in a gated community do request for a copy of the Deed Restrictions from your licensed broker or salesperson of the developer. Read and carefully examine the provisions of the Deed and determine if you can live with and abide by them.
Second, find out how much is the monthly dues to make sure that you can afford them. One of the worst things that can happen is you fail to pay the monthly dues and you are adjudged as a delinquent member of the HOA. As a delinquent member, certain rights are curtailed by the HOA.
Third, if the first two steps are positive so far, it’s time to request for a copy of the most recent audited financial statements. If the HOA office will not provide it then you can visit the HLURB Regional Office and get a copy from them. Have these financial documents reviewed by your accountant or lawyer to determine if nothing is irregular.
If the development project is new then look into the financial statement of the developer and study its track record and accomplishments of other projects. Did the developer finish on time its previous project or projects?
Fourth, find out from DHSUD’s Homeowners Associations and Community Development Bureau (HOACDB) if it is duly registered in accordance with Rep. Act No. 9904 (the Magna Carta for Homeowners and Homeowners’ Association). Moreover, check if there is litigation pending against the HOA. If there is none then that is best. However, if there is pending litigation against the HOA get the details and consult a lawyer for a better understanding of the nature of the case.
Finally, interview a homeowner who has lived in the community for more than five years. Ask him or her how it is to live in the subdivision or condominium project. How are the neighbors? Are the amenities top-rated and properly maintained? How is the security situation? Are pets allowed in the individual unit, in case of condominium? Carefully listen to the answers and if you are convinced that the community is an excellent place to live in for you and your family then you have found your new home.
Carefully research and study the pros and cons of living in your chosen gated community. Remember, the quality of the community affects the quality of your life. Good luck.
——-
Atty. Jojo is a real estate attorney, an estate planning attorney, a licensed real estate broker, and a PRC-accredited Lecturer/ Speaker for Training Programs in Real Estate. He is committed to helping new and veteran real estate service practitioners be well-informed of the latest laws, rules, regulations, and information relevant to the real estate service sector.
“For many travelers, being thrust into an unfamiliar place returns them to a purer state of being.”
– Melissa Biggs Bradley, Founder and CEO of Indagare
By Realttorney®
Mendez is part of the third Growth Area, under the Cavite Provincial Development and Physical Framework Plan 2021 – 2030, known as Metro Tagaytay or the Tourism Haven and Food Basket of the Province. This third Growth Area is composed of Indang, Amadeo, Alfonso, Maragondon, three other municipalities, and one city, which will be featured in subsequent articles in the following weeks.
This is the fifth part of the series where we explore each LGU belonging to the Metro Tagaytay area. We share our experiences as we travel and visit the Metro Tagaytay area in the past to inform you of the interesting facts, business opportunities, and the state of the real estate in each LGU.
According to Wikipedia, Mendez is a 4th class municipality located in the southern part of the province of Cavite, Philippines. It is the smallest town in the Metro Tagaytay area in terms of land area – which is approximately 22 square kilometers. It is bounded to the north and east by Indang, to the South by Tagaytay City, and to the West by Alfonso.
While it may be the smallest town in upland Cavite, and less renowned as other tourist destinations like its neighbors to its South, Mendez has plenty to offer to its almost 35,000 residents and interested real estate investors seeking bargain deals. Here are some fascinating facts about Mendez, Cavite.
Official Name and History: Mendez is officially known as the Municipality of Mendez-Nuñez. It was originally known as “Gahitan“, one of the many barrios of Indang during the Spanish era. The name was derived from the word “gahit” meaning “to cut“, because the people then had to cut down tall and thick cogon grass that abounded in the place to clear areas for agricultural and residential purposes.
The history of Mendez, according to Wikipedia, says that when the houses in Gahitan increased in number the sitio graduated to become a barrio and finally a full-fledged town on 1 December 1875, thanks to Governor-General Jose Malcampo y Monje (1874-1877). Governor Malcampo incorporated the three barrios of Gahitan, Palocpoc, and Anuling into one independent municipality called Mendez-Nuñez, after a Spanish naval officer and close friend, Commodore Casto Mendez Nuñez.
Pedro Aure was the gobernadorcillo of Mendez during its first year as a municipality in 1876. Cayetano Aure, perhaps a relative of Pedro, was the first and only capitan municipal of Mendez during the First Philippine Republic (1899-1901).
Mendez continued to be a municipality from 1875 to October 15, 1903, when, under Act No. 947 of the Philippine Commission reduced the 23 municipalities of Cavite to eleven. Mendez and Bailen (now General Emilio Aguinaldo) were incorporated into the municipality of Alfonso.
But twelve (12) years later, on January 1, 1915, Mendez regained its independent status as a municipality of the Province of Cavite.
Geographic Appeal and Accessibility: Mendez is accessible via the Trece-Indang-Mendez-Tagaytay Road (actually a highway) if one is coming from the Capitol Compound in Trece Martires City. Another route is from the Aguinaldo Highway Exit of the Cavite-Laguna Expressway (CALAX) in Silang, one can use Aguinaldo Highway to Tagaytay City, and turn right at the Tagaytay-Alfonso Bypass Road.
When you reach the Indang-Mendez-Tagaytay Road intersection, turn right, and in less than 2 minutes you’ll be crossing the border of Mendez and Tagaytay City. When the bridge that connects Brgy. Patutong Malaki North and Brgy. Guinhawa North is fully constructed, one can use this to reach Brgys. Palocpoc, Anuling, and Panungyan via the Tagaytay-Alfonso Bypass Road, as well.
Several major road projects are planned by the Department of Public Works and Highways (DPWH) that will improve the mobility of residents and transients in the Metro Tagaytay area of Cavite. If all goes as planned, one of the interchanges of the Cavite-Tagaytay-Batangas Expressway (CTBEX) will be situated in the Municipality of Mendez-Nuñez, in between the interchanges in Amadeo, Cavite and Tagaytay City.
The increase in mobility and accessibility of real properties often brings an increase in the value of said real properties. So, expect a steady appreciation of land values in the entire Municipality of Mendez.
Meanwhile, the geographic location of Mendez is an advantage that it shares with the neighboring municipalities bounded by Tagaytay City. The cool climate of Mendez – described as tropical highland – is unmatched compared to other parts of Indang, Amadeo, and Silang with lower elevation. As such, events places, and resort-type developments have opened their doors to weary urban dwellers from the National Capital Region.
Economic Growth and Potential: Mendez is now home to the newly opened Mendez Specialist Medical Center along the Indang-Mendez-Tagaytay Road. Moreover, about 300 meters away from the hospital, a branch of McDonald’s opened its doors to hungry constituents of the Municipalities of Alfonso, Indang, and Mendez.
This shows the increased level of economic activity and great potential for growth by this 4th class Municipality. Imagine the types of business that will be established once the alignment of the Mendez Interchange of CTBEX has been confirmed. Commercial real estate ventures will increase. And, it may bring PEZA-registered ecozones near the exits of the interchange which can cater to the pool of qualified employees who are graduates of the Cavite State University Main Campus located in Indang, Cavite – less than 9 kilometers away from Mendez.
Potential as a High-Value Crops Center: Mendez was known for its agricultural products, particularly coffee, coconut, pineapple, and chayote. In the 1970s, the Municipalities of Amadeo, Indang, Mendez, and Alfonso had thousands of coffee trees that were harvested and brought a lot of wealth to its farmers. But those days have long been gone.
Still, the fertile soil and favorable climate make Mendez an ideal location for farming, which contributes to the local economy and provides employment opportunities for residents. The cool climate of Mendez is conducive to the planting and growing of strawberries and other highland vegetables or high-value commercial crops.
Under the provisions of the High-Value Crops Development Act of 1995 [Rep. Act No. 7900], “High-value crops (HVC)” are crops other than traditional crops which include, but are not limited to: coffee and cacao, fruit crops (citrus, cashew, guyabano, papaya, mango, pineapple, strawberry, jackfruit, rambutan, durian, mangosteen, guava, lanzones, and watermelon), root crops (potato and ubi), vegetable crops (asparagus, broccoli, cabbage, celery, carrots, cauliflower, radish, tomato, bell pepper, and patola), legumes, pole sitao (snap beans and garden pea), spices and condiments (black pepper, garlic, ginger, and onion), and cutflower and ornamental foliage plants (chrysanthemum, gladiolus, anthuriums, orchids, and statice).
There are numerous idle lands in the Municipality of Mendez, as well as nearby municipalities. When branded differently, this sleepy town can be a powerhouse High-Value Crops Center due to its favorable climate and abundance of water resources.
Despite the abundance of water, this important resource must be protected and conserved since the various waterways traversing the Municipality of Mendez-Nuñez are part of the Labac-Alemang River Watershed (LARW). It is important to know that watersheds are categorized under protected areas declared under the National Integrated Protected Areas System (NIPAS) Act of 1992[Rep. Act No. 7586].
Healthy and protected watersheds provide critical services to humans, such as clean drinking water, productive fisheries, and outdoor recreation, that support local economies, and enhance the environment and the quality of life of the inhabitants. Hence, real estate investors must plan their investments in Mendez and most of the highlands of Cavite with this important concept or principle in mind.
Ideal Real Estate Projects and Investments in Mendez
Given its unique location and importance in protecting the Labac-Alemang River Watershed, Mendez should encourage these types of real estate development and investment:
Agricultural Estates: Despite its small land size, the Municipality of Mendez can establish model farms of high-value crops that can be replicated in the nearby towns of Indang and Amadeo. These farms can cross borders to achieve economies of scale in the production of the chosen HVCs.
However, an important feature of these estates should be the creation of numerous small water-impounding sites or areas to catch surface water during the rainy season and accumulate water that can possibly refill underground aquifers to strengthen the capacity of the watershed.
Finally, these estates must likewise implement processes that would prevent the contamination of the water resources by pesticides and other agricultural inputs. Or better yet, they should go organic if possible.
Farm Tourism Sites: With the benefits of the Farm Tourism Development Act of 2016 [Rep. Act No. 10816], investors can establish farm tourism camps in Mendez that allow visitors and tourists to visit, get involved in farm activities, and enjoy and learn rural lifestyle. This is in line with making Mendez the High-Value Crops Center of Metro Tagaytay, as well.
BPO Business Centers: With the opening of the Mendez Interchange of the CTBEX, the creation of the BPO-Technology Hub near the exits is an exciting opportunity. Why? Low cost of labor, low cost of living for the employees, and the dispersal of business and economic activity in the rural areas are positive factors for investors to consider.
Finally, PEZA-registered Agro-Industrial Zones can also be established near the Mendez Interchange. The small land area of Mendez will not hamper this since the lands in Indang can be utilized for expansion for such a venture since the latter is the Agro-Industrial Hub of the Metro Tagaytay Area.
In conclusion, Mendez-Nuñez, Cavite offers solid opportunities for real estate investments that will protect the environment and maintain the health of the watershed while at the same time introducing high-income industries that take advantage of the human resources of nearby municipalities. By leveraging these unique attributes, investors can establish business ventures that not only generate substantial returns but also contribute to the sustainable development and prosperity of this unfamiliar town in the Province of Cavite.
If this article resonates with you, let us start a conversation that may lead to providing employment opportunities to this part of the Metro Tagaytay area.
——-
Atty. Jojo is a real estate attorney, an estate planning attorney, a licensed real estate broker, and a PRC-accredited Lecturer/ Speaker for Training Programs in Real Estate. He is committed to helping new and veteran real estate service practitioners be well-informed of the latest laws, rules, regulations, and information relevant to the real estate service sector.
“Per World Bank estimates, the Philippines’ real property taxes account for only 0.37% of the Gross Domestic Product (GDP) with an overall collection efficiency of 71%.”
– OIC-Director Brenda L. Miranda, BLGF Local Fiscal Policy Service
House approves the Real Property Valuation and Assessment Reform Bill (https://blgf.gov.ph)
By Realttorney®
Sometime on April 2-4, 2013, ranking officials of our Department of Finance (DOF) presented “Property Tax Reforms in the Philippines” during the Fourth IMF-Japan High-Level Tax Conference at Hotel Nikko, Tokyo, Japan. During this event, the Philippines identified eight (8) Issues and Challenges regarding our property-related tax administration system.
The eight are as follows: (1) lack of uniform property valuation systems and methodology; (2) outdated real property values; (3) political interference in property valuation; (4) limited use of information technologies in the appraisal process; (5) multiple taxes on property ownership and transfers; (6) relatively high transfer taxes, which discourage formal transactions; (7) weak enforcement of property-related taxes; and (8) no provision for formal education and training of assessors/appraisers
The promulgation and adoption of DOF Department Order No. 37-09 [Philippine Valuation Standards, 1st Edition] on October 19, 2009, continues to address the first item above, while the passage of Rep. Act No. 9646 addressed the last item on the list.
Meanwhile, the various Joint Memoranda of the DOF and the DILG enjoined all Local Government Units (LGUs) regarding the regular preparation of Schedule of Market Values (SMV) and the conduct of general revision of property assessment in their respective jurisdictions.
Way back on May 12, 2012, the House of Representatives passed the Valuation Reform Bill [House Bill No. 6044] to address most of the 8 Issues and Challenges mentioned above. However, the Senate of the Philippines failed to pass the counterpart bill at that time until recently.
In the 2022 State of the Nation Address (SONA), Pres. Marcos, Jr. identified the Real Property Valuation and Assessment Reform Act (RPVARA) as one of his Administration’s priority legislations, and a key tax reform under the Comprehensive Tax Reform Program under the Duterte Administration.
On December 12, 2022, the House of Representatives passed on third and final reading, the Real Property Valuation and Assessment Reform bill [House Bill No. 6558]. Thankfully, this time, the Senate of the Philippines had counterpart bills on hand.
In the Explanatory Note of Senate Bill No. 897, filed by Sen. Pia S. Cayetano on July 26, 2022, she stated that “there are various agencies conducting or requiring property valuation, with each agency using their own system and methodology of valuation” of the economy, including the real estate industry. Understanding these implications is crucial for real estate professionals, investors, and policymakers.
Senate Bill No. 2386 was passed on the third and final reading on March 11, 2024, via a unanimous vote by all 23 Senators present. Both Houses of Congress ratified the final version of the bill on March 20, 2024. The President approved the bill as Republic Act No. 12001 on June 13, 2024.
As a real estate service practitioner (RESP), what do you need to know about this crucial tax reform program that was signed into law in June 2024?
1. Updated and Fairer Property Valuation: According to RPVARA, it is the policy of the State to promote the development of a just, equitable, and efficient real property valuation system. Thus, it aims to establish uniform appraisal standards and procedures. This should lead to more accurate and consistent valuations across the country, reducing unfair tax burdens on property owners.
According to Ma. Pamela Quizon, Director of the Bureau of Local Government Finance (BLGF), this reform bill will address the current inefficiencies in the system such as overlapping valuation. She stressed that there are currently 23 national government agencies requiring valuations of 1,715 LGUs.
However, each government agency uses its own systems and methodologies which is causing wide disparities between zonal values, market values, and private appraisers’ values. Thus, leading to varying and multiple values for the same parcel of land or real property.
RPVARA strengthened and expanded the powers and functions of the BLGF as the primary or lead implementing agency of this reform bill. The BLGF shall be the agency responsible for ensuring that valuations or revaluations are completed per standards outlined in the RPVARA.
Finally, under the RPVARA, an updated schedule of market values (SMV) will be used as the basis for local and national land and property-related taxes. There shall be only one valuation for a specific real property.
The SMV refers to a table of base unit market values for all kinds of real property, except machinery within an LGU, prepared by assessors according to existing laws, rules and regulations. LGUs are mandated to update SMV and its revision once every 3 years under Section 219 of the Local Government Code of 1991, as amended.
2. Transparency and Efficiency: RPVARA shall develop and maintain the Real Property Information System (RPIS). This is an up-to-date electronic database of the sale, exchange, lease, mortgage, donation, transfer, and all other real property transactions and declarations in the country and on the cost of construction or renovation of buildings and other structures, and on prices of plant, machinery, and equipment.
For this purpose, the BLGF shall require the mandatory submission of necessary documents from the concerned officials or employees of government agencies and instrumentalities, and LGUs. Towards this end, the BLGF shall establish mechanisms for the electronic submission of the required documents. Upon the creation of the RPIS, the private sector may access the database subject to the guidelines of the BLGF and the payment of a reasonable amount as an administration fee.
This electronic database will centralize data on real estate transactions and shall be an important tool for all valuers – especially private appraisers who can now accurately prepare Appraisal Reports based on actual data of “comparables” in a given property location. No more educated guesses with the aid of Google and real estate listing sites.
3. Streamlined Government Services: The RPVARA mandates all LGUs to automate their real property tax administration operations, such as but not limited to, tax mapping technology, maintaining software-enabled valuation systems, undertaking regular data cleansing, and computerized records management, with the guidance of the BLGF, in coordination with the Department of Information and Communications Technology (DICT). This could benefit the clients of RESPs involved in transactions requiring these services.
Moreover, automating processes through the RPIS could expedite government activities related to property, such as right-of-way acquisition and land transfer tax administration which will redound to the benefit of its stakeholders.
4. Taxpayer Relief: Republic Act No. 12001 grants a two-year amnesty on penalties, surcharges, and interest on real property taxes and special levies that were unpaid before the Act took effect (Section 30). The amnesty may be availed of within two years after the Act’s effectivity. A delinquent owner may pay the taxes in one lump sum or in installments. The amnesty does not apply to properties already sold at public auction for tax delinquency, properties whose delinquencies are covered by a compromise agreement, or properties subject to pending court cases on real property tax delinquencies. As noted above, this provision was not indicated in SBN 2386 or HBN 6558, but it appears in the enacted law, and it is a welcome addition to this important piece of legislation.
This provides an opportunity for clients to settle outstanding tax obligations without extra charges and fend off the levy of the property and its public auction by the concerned LGU. It is a timely relief for landowners as they battle the effects of inflation and high-interest rates from 2021 up to the present. Because the window runs for two years from the Act’s effectivity, clients should confirm the exact deadline with the concerned LGU.
5. Increase Collection of Real Property Taxes: The reform will broaden the tax base for local and national property and property-related taxes. With a wider tax base, the collection of real property taxes is expected to increase based on updated property values, which is most important to increase collection efficiency, and overall tax revenue by LGUs and the Bureau of Internal Revenue (BIR).
Oftentimes, outdated property values result in unrealized revenues and socio-economic benefits from delayed projects, and conflicting land values which result in right-of-way (ROW) compensation problems, lengthy court litigations arising from valuation disputes, delayed projects, and cost overruns.
With the increased collection efficiency, it is expected that LGUs will be able to translate this into better basic services for its constituents and critical infrastructure projects by the National Government based on the increased revenue-based national real property transfer taxes.
With fairer valuations and a more transparent system, RPVARA would lead to a steady increase in market values of real properties in the Philippines at regular intervals without increasing the tax rates or introducing new taxes. Therefore, it is incumbent on RESPs to advise our clients as to the timing of such increases to take advantage of relatively low prices when they desire to purchase real properties.
In conclusion, the Real Property Valuation and Assessment Reform Act brings several positive changes in the valuation system and the real estate sector in the Philippines in general. The reform bill shall implement a more efficient valuation system and will use a single valuation base, which will eliminate wide disparities caused by overlapping valuations.
This would lead to consistency in real property valuation as well as the predictability of valuation. As such, the adoption of true market-based values for taxation purposes will increase revenues without necessarily adopting new tax measures.
RPVARA endeavors to increase the capacity of the government to generate revenues from real property through the RPT, national government real property transfer taxes, and other related taxes. In addition, RPVARA aims to reduce government costs particularly unnecessary expenses incurred due to conflicting appraisals which lead to court litigations, project delays, and cost overruns.
As RPVARA aims to implement uniform standards and efficient processes in the real property tax system, the government hopes that this will instill more confidence in the country’s real estate industry. In the end, the government desires to motivate and inspire real estate investors and public confidence because the valuation is done professionally, properly, and following current local and international standards.
——-
Atty. Jojo is a real estate attorney, an estate planning attorney, a licensed real estate broker, and a PRC-accredited Lecturer/ Speaker for Training Programs in Real Estate. He is committed to helping new and veteran real estate service practitioners be well-informed of the latest laws, rules, regulations, and information relevant to the real estate service sector.
— Seneca, Moral Letters to Lucilius, Letter 1, translated by Richard Mott Gummere
By Atty. Jojo Perez | Realttorney®
[Originally published March 2, 2024 | Substantive revision prepared November 1, 2026]
Can you sell property that is still in a deceased relative’s name?
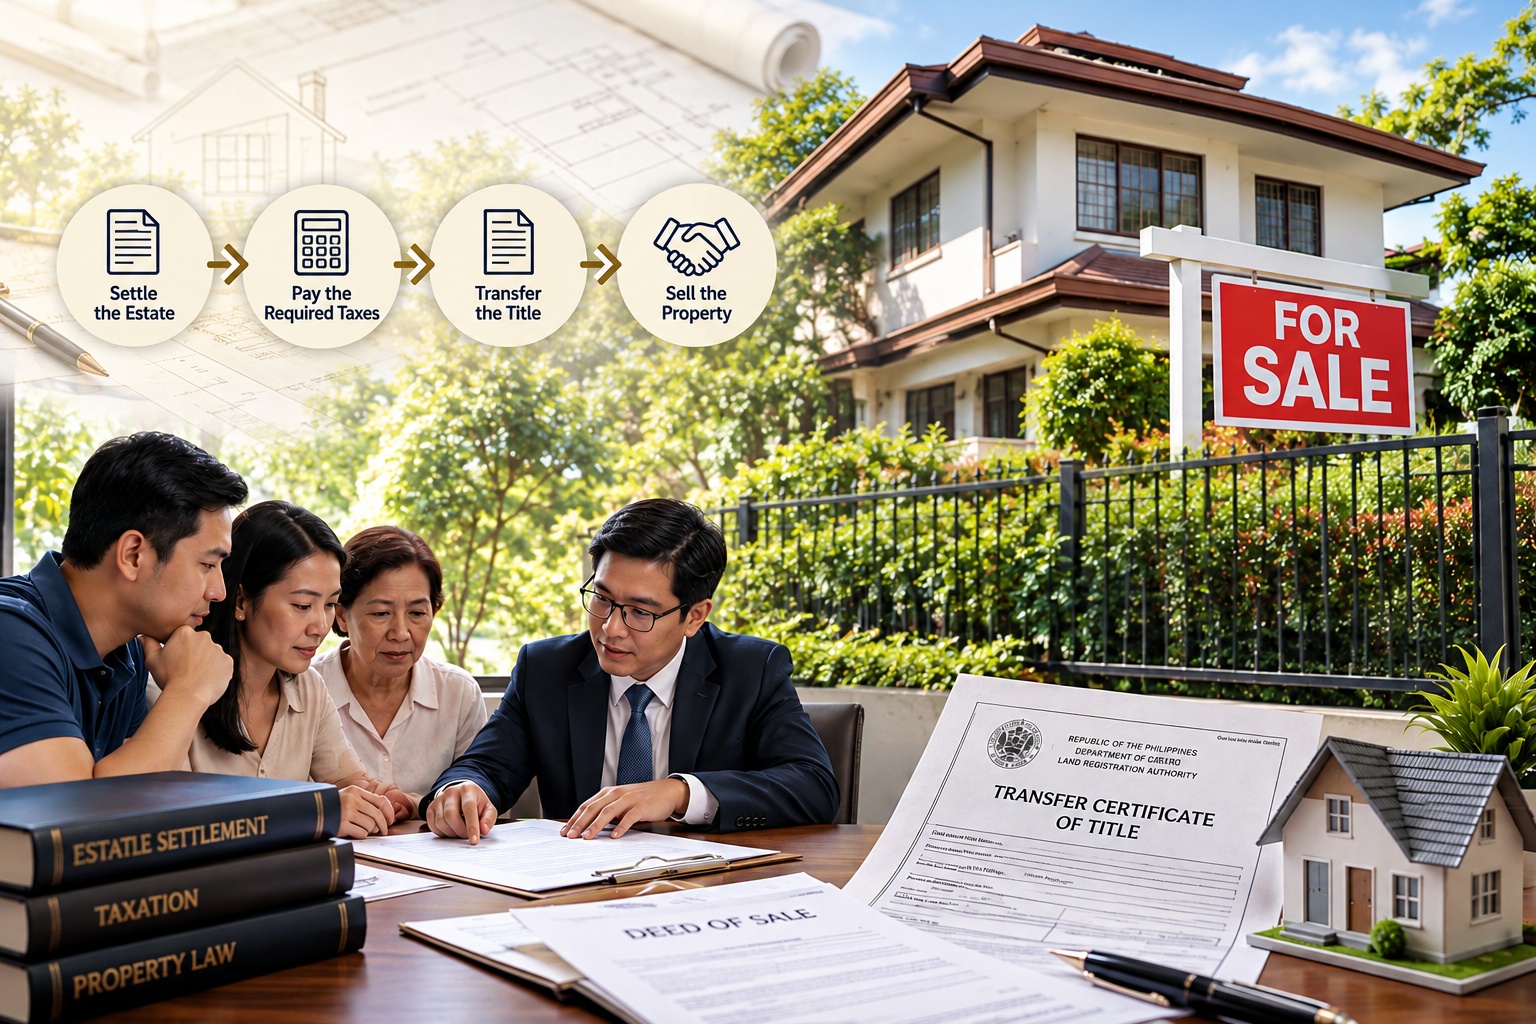
Yes, heirs may arrange the sale of inherited property in the Philippines, but they must establish their rights and authority, use the correct estate-settlement documents, and comply with the applicable tax and registration requirements. Depending on the circumstances, settlement and sale may be documented together through an extrajudicial settlement of estate with sale. A separate title in the heirs’ names is not a universal prerequisite to executing the sale documents.
Death leaves families with more than grief. It also leaves practical questions. Who may sign for the property? What if one heir is abroad? Can the buyer’s payment help fund the taxes? What happens when the family cannot agree?
Before finding a buyer or accepting a deposit, understand what the family owns, who must participate, and which process applies. This guide focuses on an agreed extrajudicial settlement of an estate without a will. A will, unresolved debts, disputed heirship, or a proposed sale involving a minor’s share requires separate legal consideration.
What changes when the registered owner dies
The title may remain in the deceased person’s name, but that does not mean the heirs have no rights until a new title is issued. Under Article 777 of the Civil Code, successional rights pass at death. Where there are several heirs, the estate is generally held in common before partition, subject to payment of the deceased’s debts. Ownership rights, authority to sell the entire property, and registration of the buyer’s title are related but distinct issues. Civil Code, Articles 777 and 1078.
Never prepare a deed making it appear that the deceased owner is still alive and personally selling the property. The proper parties must sign in their actual capacities. A notarized document cannot cure a fabricated signature or missing authority.
Step 1: Identify the heirs and the deceased owner’s actual interest
Do not assume that the children are the only heirs. Establish the family relationships, whether a spouse survives, and whether an heir has also died. A later death may require examination of another estate and another set of successors.
Check whether the property was exclusively owned by the deceased, belonged to the spouses’ property regime, or was co-owned with someone else. A surviving spouse’s own interest must be distinguished from that spouse’s inheritance. The name printed on the title does not, by itself, answer every marital-property question.
Gather the death certificate, relevant birth and marriage records, title, tax declarations, and any documents affecting ownership. Investigate inconsistent names, missing records, annotations, mortgages, occupants, and pending disputes before drafting the settlement. The property due diligence checklist provides a useful starting point for buyers.
Step 2: Confirm that extrajudicial settlement is appropriate
Under Rule 74, Section 1, an agreed extrajudicial settlement is available when the deceased left no will, has no debts, and the heirs are all of age or minors are represented by judicial or legal representatives duly authorized for the purpose. If there is only one heir, the appropriate instrument may be an affidavit of self-adjudication. Ende v. Roman Catholic Prelate.
Every heir must be accounted for and properly participate in the agreed settlement, personally or through valid representation. The heirs must address existing liabilities and agree on a lawful settlement. A minor cannot simply sign an SPA, and a parent’s signature should not be assumed to supply every authority needed to dispose of the child’s property. Obtain advice about representation and any necessary court approval.
If there is a will, it must be dealt with through the applicable probate process. If heirship, ownership, debts, or the proposed division is disputed, a court proceeding, or another appropriate remedy may be needed. Do not conceal a will or omit a family member merely to make the paperwork easier.
Step 3: Agree on the sale terms and who may represent the heirs
One trusted representative can make negotiations manageable. Trust, however, should be supported by a clear written mandate or authority.
Before marketing the property, agree on the proposed price, payment terms, tax and expense allocation, brokerage commission, possession, and distribution of the net proceeds. Distinguish authority to negotiate from authority to sign a settlement or sale and authority to receive the purchase money.
If an heir cannot personally sign, obtain an appropriately worded Special Power of Attorney. It should identify the property and expressly cover the acts the representative is expected to perform. Verify that the authority remains effective before signing and closing. A family spokesperson cannot automatically bind the other heirs.
For an heir abroad, distinguish two usual routes: acknowledgment before an authorized Philippine consular officer, or execution before a foreign notary followed by the applicable apostille or authentication process. The correct route depends on the country and receiving office. Foreign notarization alone should not be assumed sufficient. DFA apostille and consular guidance.
Electronic notarization has separate requirements under the Supreme Court’s rules, including a limited route for principals at Philippine foreign posts. It is not an ordinary video call with any notary. Confirm that the proposed service and document comply with the rules and are accepted for the transaction. The Effects of Electronic Notarization in Real Estate Transactions.
Step 4: Choose the settlement and sale documents
There are two common structures to consider.
Settlement followed by a separate sale. The heirs first document and process the settlement, then convey the property through a separate deed of sale. The particular registration sequence should be established before the parties sign or commit funds.
Extrajudicial settlement of estate with sale. Where legally appropriate, the heirs settle the estate and convey the identified property in a combined instrument. The Land Registration Authority publishes a standard form for an extrajudicial settlement with absolute sale. This structure does not remove either the estate-transfer or sale-transfer requirements. LRA downloadable forms.
The choice is not determined solely by whether the deceased owned one property or several. Consider the entire estate, the property being sold, the heirs’ agreement, outstanding requirements, and the BIR and Registry of Deeds processing route. Do not omit other estate assets because the buyer wants only one parcel.
The settlement must comply with the applicable formalities. Rule 74 requires publication of the fact of the settlement once a week for three consecutive weeks in a newspaper of general circulation. Its requirements also include a bond concerning personal property, where applicable. Publication does not make an excluded heir’s rights disappear. Ende v. Roman Catholic Prelate.
Step 5: Settle the applicable taxes and obtain the BIR clearances
Estate tax and taxes arising from a later sale are separate matters. Do not assume that paying one settles the other.
For deaths on or after January 1, 2018, the regular estate tax is six percent (6%) of the net taxable estate after applicable deductions. For earlier deaths, apply the estate-tax law in force at the date of death, including its allowable deductions and any lawfully applicable amnesty or other relief. The estate-tax return is generally due within one year of death under the TRAIN law (Rep. Act No. 10963); a late settlement requires assessment of the relevant additions and available remedies. BIR Revenue Regulations 12-2018.
An estate may still need to file a return and secure the appropriate BIR clearance for registrable property even where deductions leave no estate tax payable. The electronic Certificate Authorizing Registration, or eCAR, is a tax clearance used in the registration process. It is not a certificate guaranteeing ownership or curing an invalid settlement.
For the sale, determine the property’s tax classification and applicable taxes rather than assuming capital gains tax applies to every transaction. Include documentary stamp tax where applicable, local transfer tax, registration charges, and any required real-property-tax clearance in the closing plan. Confirm the documents and eCAR requirements for each transfer with the relevant offices.
If sale proceeds are needed to fund the estate obligations, arrange the payment safeguards before signing. Indicate clearly who advances the money, where it goes, what proves payment, and what happens if the transfer cannot proceed. Do not promise a fixed processing period or automatic release of a particular number of eCARs without checking the actual transaction.
Is a new estate tax amnesty available?
Legislative update reviewed November 1, 2026. Do not treat a pending bill as an available tax amnesty. The latest Senate hearing update verified for this article is the October 23, 2026 statement issued through Senator Panfilo Lacson’s office. It describes proposals under consideration, rather than an enacted replacement program.
The previous amnesty and the 2026 BIR clarification
Republic Act No. 11956 extended the previous estate-tax-amnesty period until June 14, 2025 and covered qualifying estates of persons who died on or before May 31, 2022. The BIR subsequently referred to June 16, 2025, as the operative deadline. Those dates are historical and should not be advertised as a current invitation to apply. Republic Act No. 11956.
BIR Revenue Memorandum Circular No. 33-2026 clarified that failure to submit proof of estate settlement by that deadline does not invalidate an amnesty application, although the proof remains necessary for the eCAR. It also addresses approved installment arrangements and undeclared properties. This clarification should not be read as reopening the application period for everyone. Anyone who previously applied should have the return, payment records, and remaining requirements reviewed. BIR RMC 33-2026 official digest.
What the Senate was considering
At the October 23 hearing, Lacson’s office reported consideration of multiple estate-tax measures and a House proposal to extend the earlier amnesty. His Senate Bill No. 1889 instead proposes a new amnesty covering estates of persons who died on or before December 31, 2025, at 6 percent of the net estate. That proposed coverage is not an existing entitlement. Senate Bill 1889 proposal and explanatory statement.
The hearing raised concerns about proof of death, documentary delays, and payment deadlines. The same statement says Senate President Sherwin Gatchalian generally supports amnesty but questioned why taxpayers still struggle to pay after repeated opportunities, including whether the 6 percent rate is too expensive. It would therefore be inaccurate to describe his position simply as opposition to any new amnesty. October 23 hearing statement.
The practical advice is to prepare the documents now and have the present liability assessed. Do not assume that a proposed deadline, coverage date, rate, or waiver will survive the legislative process. Before relying on new relief, verify the enacted law, its effectivity, and the applicable BIR implementation. Estate tax amnesty must also be distinguished from local real-property-tax relief.
Step 6: Complete registration and the agreed turnover
Signing the documents and paying the taxes are not the final steps. Submit the proper instruments, BIR clearances, title documents, publication evidence, local tax documents, and other applicable requirements to the Registry of Deeds. Coordinate the local transfer-tax and registration deadlines rather than leaving them until the end.
Follow through on the resulting title and updated tax declaration. Separately document possession, keys, occupants, unpaid charges, and release of the purchase-price balance. A successful registration does not physically remove an occupant or resolve a boundary or access dispute.
A hypothetical case study involving an overseas heir
Assume a widower dies without a will, leaving a house and lot that he exclusively owned. His wife died earlier, her estate has already been properly dealt with, and records establish that his three adult children are his only heirs. Assume there are no outstanding debts. Two children live in Metro Manila; the third lives abroad.
The children agree to sell. They first verify the title and supporting records. The overseas child executes an appropriate SPA through the applicable consular or foreign-notarization route. The family and buyer obtain advice on using a combined settlement with sale or separate instruments, arrange publication and tax compliance, and agree in writing how any funds advanced for taxes will be protected. Registration and turnover follow once the requirements are met.
Change one fact and the solution may change. A disputed heir, an unresolved earlier estate, a minor, a will, or a defective SPA may prevent this straightforward route.
A buyer’s checklist before paying
Verify the title, annotations, actual possession, boundaries, access, and intended use.
Establish the deceased owner’s interest and identify every person whose participation or authority is needed.
Check the settlement route and independently verify the identities, signatures, and representative’s powers.
Obtain a written estimate and allocation of taxes and expenses, with safeguards for any advance payment.
Set clear document, registration, payment, and turnover milestones, including what happens if a condition fails.
Verify the buyer’s legal eligibility to acquire the property. Being a relative does not, by itself, make a foreign buyer qualified to own Philippine land.
Do not rely on a notarized SPA merely because someone says everyone signed it. If a supposed signatory has died or authority has changed, the transaction must be reviewed before it proceeds.
Frequently asked questions (FAQs)
Must the heirs get a new title before signing a sale?
Not in every case. A legally appropriate settlement with sale can combine the documentation. The estate and sale requirements still have to be satisfied before the buyer can complete registration.
Can one heir sell the entire property?
One heir’s signature ordinarily cannot bind all co-heirs without authority. Selling an undivided hereditary interest is a different transaction from selling the entire property; it can raise partition and redemption issues that need separate advice.
What if one heir refuses to sell?
The other heirs should not sign for that person without authority. Consider negotiation, partition, or the appropriate court remedy rather than misrepresenting consent.
How long does the process take?
There is no reliable universal timetable. Missing records, multiple estates, overseas execution, disputes, tax issues, and registration requirements can materially affect completion. Obtain a case-specific work plan.
Before you put the property on the market
The first useful step is to establish the estate’s legal and documentary position. Know the heirs, identify the proper settlement route, and work out the taxes and closing arrangements. A buyer should be able to see how the transaction will reach a valid, registrable transfer.
Do not let the process drift. Every deferred heir signature, missing record, and unpaid tax is a problem that grows while the family waits.
If you need help settling an estate or evaluating a proposed sale of inherited property, book a consultation with Realttorney®. Bring the available title, death, and civil registry records, tax declarations, and any settlement or amnesty documents already filed.
This article provides general information on Philippine estate settlement and property transactions. The appropriate documents, taxes, authority, and procedures depend on the entire estate and the circumstances of the parties.
Atty. Jojo is a real estate attorney, an estate planning attorney, a licensed real estate broker, and a PRC-accredited Lecturer/ Speaker for Training Programs in Real Estate. He is a Chartered Trust and Estate Planning (CTEP®) professional who is committed to educating Filipinos about the value and importance of having an estate plan in their lives.