
“While we are postponing, life speeds by.”
— Seneca, Moral Letters to Lucilius, Letter 1, translated by Richard Mott Gummere
By Atty. Jojo Perez | Realttorney®
[Originally published March 2, 2024 | Substantive revision prepared November 1, 2026]

Can you sell property that is still in a deceased relative’s name?
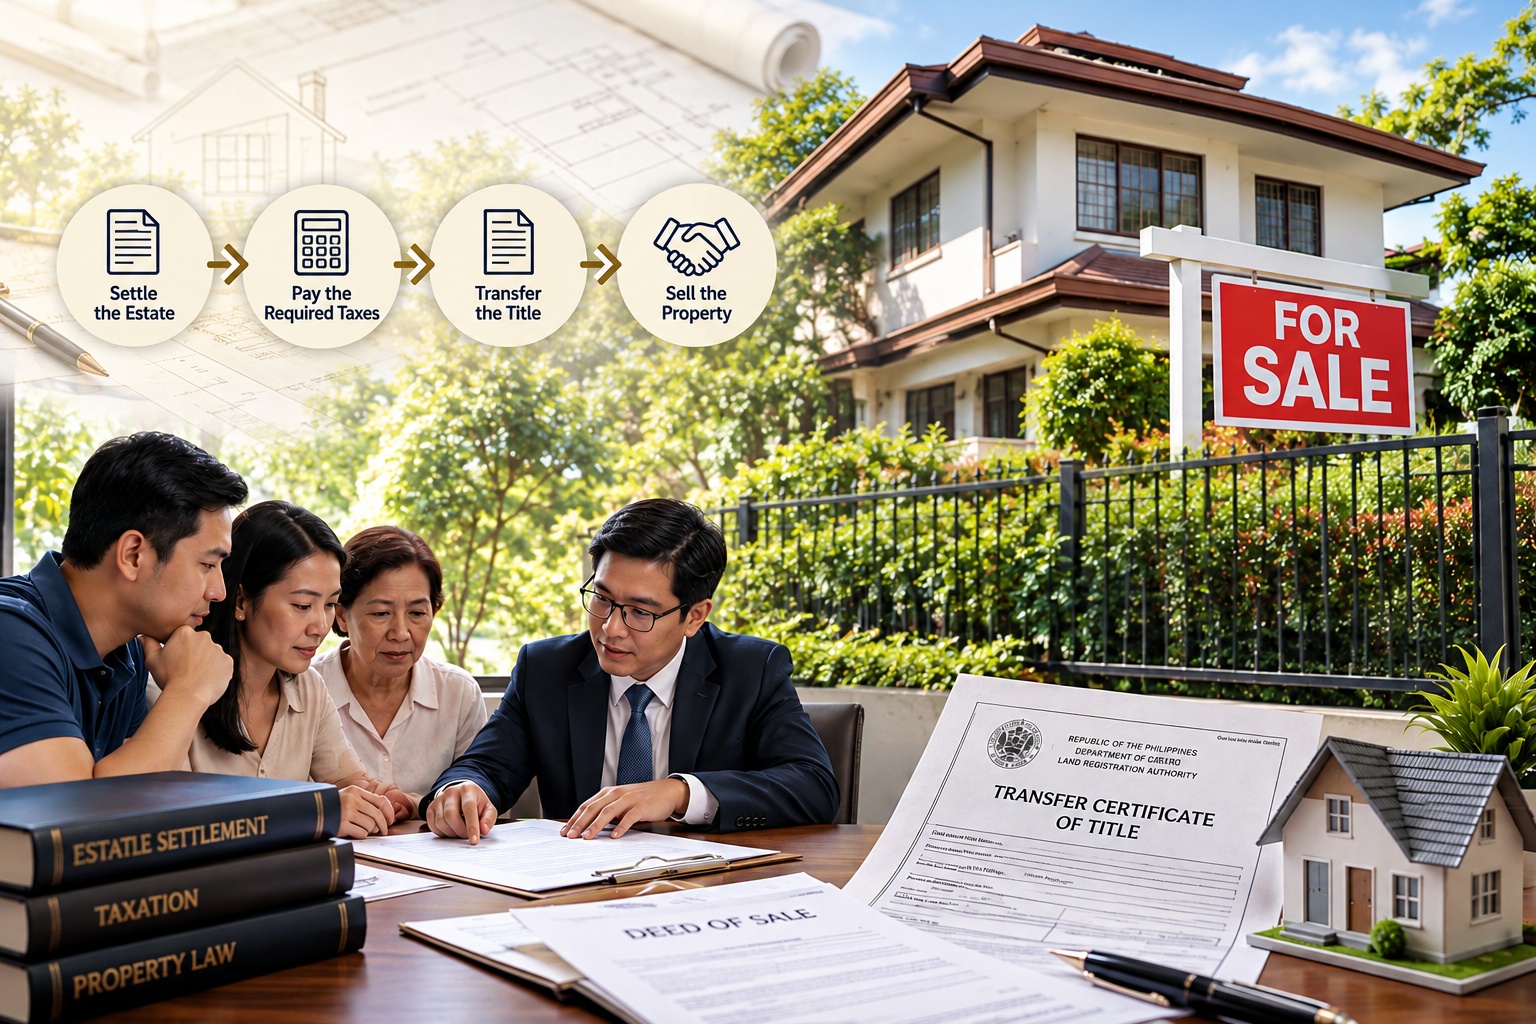
Yes, heirs may arrange the sale of inherited property in the Philippines, but they must establish their rights and authority, use the correct estate-settlement documents, and comply with the applicable tax and registration requirements. Depending on the circumstances, settlement and sale may be documented together through an extrajudicial settlement of estate with sale. A separate title in the heirs’ names is not a universal prerequisite to executing the sale documents.
Death leaves families with more than grief. It also leaves practical questions. Who may sign for the property? What if one heir is abroad? Can the buyer’s payment help fund the taxes? What happens when the family cannot agree?
Before finding a buyer or accepting a deposit, understand what the family owns, who must participate, and which process applies. This guide focuses on an agreed extrajudicial settlement of an estate without a will. A will, unresolved debts, disputed heirship, or a proposed sale involving a minor’s share requires separate legal consideration.
What changes when the registered owner dies
The title may remain in the deceased person’s name, but that does not mean the heirs have no rights until a new title is issued. Under Article 777 of the Civil Code, successional rights pass at death. Where there are several heirs, the estate is generally held in common before partition, subject to payment of the deceased’s debts. Ownership rights, authority to sell the entire property, and registration of the buyer’s title are related but distinct issues. Civil Code, Articles 777 and 1078.
Never prepare a deed making it appear that the deceased owner is still alive and personally selling the property. The proper parties must sign in their actual capacities. A notarized document cannot cure a fabricated signature or missing authority.
Step 1: Identify the heirs and the deceased owner’s actual interest
Do not assume that the children are the only heirs. Establish the family relationships, whether a spouse survives, and whether an heir has also died. A later death may require examination of another estate and another set of successors.
Check whether the property was exclusively owned by the deceased, belonged to the spouses’ property regime, or was co-owned with someone else. A surviving spouse’s own interest must be distinguished from that spouse’s inheritance. The name printed on the title does not, by itself, answer every marital-property question.
Gather the death certificate, relevant birth and marriage records, title, tax declarations, and any documents affecting ownership. Investigate inconsistent names, missing records, annotations, mortgages, occupants, and pending disputes before drafting the settlement. The property due diligence checklist provides a useful starting point for buyers.
Step 2: Confirm that extrajudicial settlement is appropriate
Under Rule 74, Section 1, an agreed extrajudicial settlement is available when the deceased left no will, has no debts, and the heirs are all of age or minors are represented by judicial or legal representatives duly authorized for the purpose. If there is only one heir, the appropriate instrument may be an affidavit of self-adjudication. Ende v. Roman Catholic Prelate.
Every heir must be accounted for and properly participate in the agreed settlement, personally or through valid representation. The heirs must address existing liabilities and agree on a lawful settlement. A minor cannot simply sign an SPA, and a parent’s signature should not be assumed to supply every authority needed to dispose of the child’s property. Obtain advice about representation and any necessary court approval.
If there is a will, it must be dealt with through the applicable probate process. If heirship, ownership, debts, or the proposed division is disputed, a court proceeding, or another appropriate remedy may be needed. Do not conceal a will or omit a family member merely to make the paperwork easier.
Step 3: Agree on the sale terms and who may represent the heirs
One trusted representative can make negotiations manageable. Trust, however, should be supported by a clear written mandate or authority.
Before marketing the property, agree on the proposed price, payment terms, tax and expense allocation, brokerage commission, possession, and distribution of the net proceeds. Distinguish authority to negotiate from authority to sign a settlement or sale and authority to receive the purchase money.
If an heir cannot personally sign, obtain an appropriately worded Special Power of Attorney. It should identify the property and expressly cover the acts the representative is expected to perform. Verify that the authority remains effective before signing and closing. A family spokesperson cannot automatically bind the other heirs.
For an heir abroad, distinguish two usual routes: acknowledgment before an authorized Philippine consular officer, or execution before a foreign notary followed by the applicable apostille or authentication process. The correct route depends on the country and receiving office. Foreign notarization alone should not be assumed sufficient. DFA apostille and consular guidance.
Electronic notarization has separate requirements under the Supreme Court’s rules, including a limited route for principals at Philippine foreign posts. It is not an ordinary video call with any notary. Confirm that the proposed service and document comply with the rules and are accepted for the transaction. The Effects of Electronic Notarization in Real Estate Transactions.
Step 4: Choose the settlement and sale documents
There are two common structures to consider.
Settlement followed by a separate sale. The heirs first document and process the settlement, then convey the property through a separate deed of sale. The particular registration sequence should be established before the parties sign or commit funds.
Extrajudicial settlement of estate with sale. Where legally appropriate, the heirs settle the estate and convey the identified property in a combined instrument. The Land Registration Authority publishes a standard form for an extrajudicial settlement with absolute sale. This structure does not remove either the estate-transfer or sale-transfer requirements. LRA downloadable forms.
The choice is not determined solely by whether the deceased owned one property or several. Consider the entire estate, the property being sold, the heirs’ agreement, outstanding requirements, and the BIR and Registry of Deeds processing route. Do not omit other estate assets because the buyer wants only one parcel.
The settlement must comply with the applicable formalities. Rule 74 requires publication of the fact of the settlement once a week for three consecutive weeks in a newspaper of general circulation. Its requirements also include a bond concerning personal property, where applicable. Publication does not make an excluded heir’s rights disappear. Ende v. Roman Catholic Prelate.
Step 5: Settle the applicable taxes and obtain the BIR clearances
Estate tax and taxes arising from a later sale are separate matters. Do not assume that paying one settles the other.
For deaths on or after January 1, 2018, the regular estate tax is six percent (6%) of the net taxable estate after applicable deductions. For earlier deaths, apply the estate-tax law in force at the date of death, including its allowable deductions and any lawfully applicable amnesty or other relief. The estate-tax return is generally due within one year of death under the TRAIN law (Rep. Act No. 10963); a late settlement requires assessment of the relevant additions and available remedies. BIR Revenue Regulations 12-2018.
An estate may still need to file a return and secure the appropriate BIR clearance for registrable property even where deductions leave no estate tax payable. The electronic Certificate Authorizing Registration, or eCAR, is a tax clearance used in the registration process. It is not a certificate guaranteeing ownership or curing an invalid settlement.
For the sale, determine the property’s tax classification and applicable taxes rather than assuming capital gains tax applies to every transaction. Include documentary stamp tax where applicable, local transfer tax, registration charges, and any required real-property-tax clearance in the closing plan. Confirm the documents and eCAR requirements for each transfer with the relevant offices.
If sale proceeds are needed to fund the estate obligations, arrange the payment safeguards before signing. Indicate clearly who advances the money, where it goes, what proves payment, and what happens if the transfer cannot proceed. Do not promise a fixed processing period or automatic release of a particular number of eCARs without checking the actual transaction.
Is a new estate tax amnesty available?
Legislative update reviewed November 1, 2026. Do not treat a pending bill as an available tax amnesty. The latest Senate hearing update verified for this article is the October 23, 2026 statement issued through Senator Panfilo Lacson’s office. It describes proposals under consideration, rather than an enacted replacement program.
The previous amnesty and the 2026 BIR clarification
Republic Act No. 11956 extended the previous estate-tax-amnesty period until June 14, 2025 and covered qualifying estates of persons who died on or before May 31, 2022. The BIR subsequently referred to June 16, 2025, as the operative deadline. Those dates are historical and should not be advertised as a current invitation to apply. Republic Act No. 11956.
BIR Revenue Memorandum Circular No. 33-2026 clarified that failure to submit proof of estate settlement by that deadline does not invalidate an amnesty application, although the proof remains necessary for the eCAR. It also addresses approved installment arrangements and undeclared properties. This clarification should not be read as reopening the application period for everyone. Anyone who previously applied should have the return, payment records, and remaining requirements reviewed. BIR RMC 33-2026 official digest.
What the Senate was considering
At the October 23 hearing, Lacson’s office reported consideration of multiple estate-tax measures and a House proposal to extend the earlier amnesty. His Senate Bill No. 1889 instead proposes a new amnesty covering estates of persons who died on or before December 31, 2025, at 6 percent of the net estate. That proposed coverage is not an existing entitlement. Senate Bill 1889 proposal and explanatory statement.
The hearing raised concerns about proof of death, documentary delays, and payment deadlines. The same statement says Senate President Sherwin Gatchalian generally supports amnesty but questioned why taxpayers still struggle to pay after repeated opportunities, including whether the 6 percent rate is too expensive. It would therefore be inaccurate to describe his position simply as opposition to any new amnesty. October 23 hearing statement.
The practical advice is to prepare the documents now and have the present liability assessed. Do not assume that a proposed deadline, coverage date, rate, or waiver will survive the legislative process. Before relying on new relief, verify the enacted law, its effectivity, and the applicable BIR implementation. Estate tax amnesty must also be distinguished from local real-property-tax relief.
Step 6: Complete registration and the agreed turnover
Signing the documents and paying the taxes are not the final steps. Submit the proper instruments, BIR clearances, title documents, publication evidence, local tax documents, and other applicable requirements to the Registry of Deeds. Coordinate the local transfer-tax and registration deadlines rather than leaving them until the end.
Follow through on the resulting title and updated tax declaration. Separately document possession, keys, occupants, unpaid charges, and release of the purchase-price balance. A successful registration does not physically remove an occupant or resolve a boundary or access dispute.
A hypothetical case study involving an overseas heir
Assume a widower dies without a will, leaving a house and lot that he exclusively owned. His wife died earlier, her estate has already been properly dealt with, and records establish that his three adult children are his only heirs. Assume there are no outstanding debts. Two children live in Metro Manila; the third lives abroad.
The children agree to sell. They first verify the title and supporting records. The overseas child executes an appropriate SPA through the applicable consular or foreign-notarization route. The family and buyer obtain advice on using a combined settlement with sale or separate instruments, arrange publication and tax compliance, and agree in writing how any funds advanced for taxes will be protected. Registration and turnover follow once the requirements are met.
Change one fact and the solution may change. A disputed heir, an unresolved earlier estate, a minor, a will, or a defective SPA may prevent this straightforward route.
A buyer’s checklist before paying
- Verify the title, annotations, actual possession, boundaries, access, and intended use.
- Establish the deceased owner’s interest and identify every person whose participation or authority is needed.
- Check the settlement route and independently verify the identities, signatures, and representative’s powers.
- Obtain a written estimate and allocation of taxes and expenses, with safeguards for any advance payment.
- Set clear document, registration, payment, and turnover milestones, including what happens if a condition fails.
- Verify the buyer’s legal eligibility to acquire the property. Being a relative does not, by itself, make a foreign buyer qualified to own Philippine land.
Do not rely on a notarized SPA merely because someone says everyone signed it. If a supposed signatory has died or authority has changed, the transaction must be reviewed before it proceeds.
Frequently asked questions (FAQs)
Must the heirs get a new title before signing a sale?
Not in every case. A legally appropriate settlement with sale can combine the documentation. The estate and sale requirements still have to be satisfied before the buyer can complete registration.
Can one heir sell the entire property?
One heir’s signature ordinarily cannot bind all co-heirs without authority. Selling an undivided hereditary interest is a different transaction from selling the entire property; it can raise partition and redemption issues that need separate advice.
What if one heir refuses to sell?
The other heirs should not sign for that person without authority. Consider negotiation, partition, or the appropriate court remedy rather than misrepresenting consent.
How long does the process take?
There is no reliable universal timetable. Missing records, multiple estates, overseas execution, disputes, tax issues, and registration requirements can materially affect completion. Obtain a case-specific work plan.
Before you put the property on the market
The first useful step is to establish the estate’s legal and documentary position. Know the heirs, identify the proper settlement route, and work out the taxes and closing arrangements. A buyer should be able to see how the transaction will reach a valid, registrable transfer.
Do not let the process drift. Every deferred heir signature, missing record, and unpaid tax is a problem that grows while the family waits.
If you need help settling an estate or evaluating a proposed sale of inherited property, book a consultation with Realttorney®. Bring the available title, death, and civil registry records, tax declarations, and any settlement or amnesty documents already filed.
This article provides general information on Philippine estate settlement and property transactions. The appropriate documents, taxes, authority, and procedures depend on the entire estate and the circumstances of the parties.
Atty. Jojo is a real estate attorney, an estate planning attorney, a licensed real estate broker, and a PRC-accredited Lecturer/ Speaker for Training Programs in Real Estate. He is a Chartered Trust and Estate Planning (CTEP®) professional who is committed to educating Filipinos about the value and importance of having an estate plan in their lives.

